HDFC Bank UPI RuPay Credit Card vs Shaurya SBI RuPay Platinum Credit Card: Which is Better in 2026?
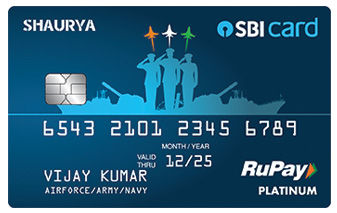
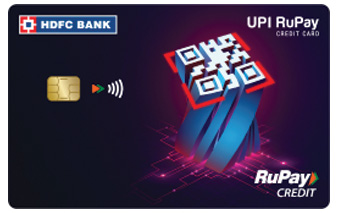 vs
In short: HDFC UPI has the lower annual fee (₹99 vs ₹250); both charge a 3.5% forex markup.
| Key facts | HDFC UPI | Shaurya SBI |
|---|---|---|
| Annual fee | ₹99 | ₹250 |
| Joining fee | ₹99 | Not listed |
| Annual fee waived | On ₹25,000 annual spend | On ₹50,000 annual spend |
| Forex markup | 3.5% | 3.5% |
From issuer benefit data, checked 23 Oct 2026. Rewards, milestones and welcome benefits are in the full table below.
The Hdfc Bank Upi Rupay Credit Card and the Shaurya Sbi Rupay Platinum Credit Card are both Rupay network cards with distinct reward structures and fee policies. HDFC's card offers tiered cashpoints on specific spends like dining and groceries, while SBI's card provides reward points with higher multipliers on categories such as dining, groceries, and movies. Both cards have similar forex markup fees but differ in joining and renewal fee waivers.
Comparison notes and quick badges use AI, grounded in the benefit data shown in the table. Confirm details on each issuer’s site.
Last updated:
| Feature | Hdfc Bank Upi Rupay Credit Card | Shaurya Sbi Rupay Platinum Credit Card |
|---|---|---|
| Bank | HDFC Bank | SBI Cards |
| Network | Rupay | Rupay |
| Joining fee | Joining Fee of Rs.99 | — |
| Annual / renewal fee | Renewal Fee of Rs.99 | Annual Fees - Rs.250 |
| Annual fee waiver | Spend Rs.25000 For Renewal Fee Waiver | Spend Rs.50000 For Waiver of Renewal Fee |
| Reward rate (headline) | 1% Cashpoints on Other Spends | Earn 1 Reward Point Per Rs.100 |
| Welcome benefit | — | Get 1000 Reward Points as Welcome Gift |
| Foreign currency markup | 3.50% - Foreign Currency Transactions | 3.5% - Foreign Currency Transactions |
Which is better for rewards?
When it comes to rewards, the Shaurya Sbi Rupay Platinum Credit Card offers a stronger value proposition for category-specific spending. It grants 5X reward points on dining, groceries, movies, and CSD, with a higher maximum cap of 5000 points, compared to HDFC's 3% cashpoints capped at 500 points on similar categories. Additionally, SBI provides a welcome benefit of 1000 reward points, which HDFC lacks. However, HDFC's card offers cashback redemption options and a straightforward earning rate on utility spends and PayZapp transactions, which might appeal to users with those spending habits.
Which is better for travel?
Both cards do not provide dedicated travel benefits such as lounge access or travel milestones. The Hdfc Bank Upi Rupay Credit Card allows redemption of cashpoints for travel through SmartBuy, while the Shaurya Sbi Rupay Platinum Credit Card does not explicitly mention travel redemption options in the data. Forex markup fees are identical at 3.5% for both cards, so neither card has an advantage for foreign currency transactions.
Which has lower effective cost?
The Hdfc Bank Upi Rupay Credit Card has a low joining and renewal fee of Rs.99 each, with a renewal fee waiver on spending Rs.25,000. In contrast, the Shaurya Sbi Rupay Platinum Credit Card has an annual fee of Rs.250, waived only after spending Rs.50,000. This makes the HDFC card more cost-effective for users with moderate spending. Both cards have similar forex fees, but SBI charges a card replacement fee of Rs.250, which is not mentioned for HDFC. Overall, HDFC's card is more beginner-friendly and economical in terms of fees.
Reward Caps and Redemption
HDFC's card caps cashpoints earnings at 500 points in key categories, which may limit rewards for high spenders, whereas SBI's card allows up to 5000 points in its 5X reward categories. Additionally, HDFC provides multiple redemption options including cashback against statement balance and travel bookings through SmartBuy, offering flexibility. SBI's redemption requires a minimum of 2000 points and is primarily for card outstanding payments.
Fee Waiver Complexity
HDFC Bank's card requires a lower spend of Rs.25,000 to waive the renewal fee compared to SBI's Rs.50,000 threshold. This makes fee management easier for moderate spenders on the HDFC card. Additionally, SBI charges a card replacement fee of Rs.250, which is not noted for HDFC, potentially adding to costs.
Who should pick Hdfc Bank Upi Rupay Credit Card?
Consider Hdfc Bank Upi Rupay Credit Card if you prefer a low-cost credit card with simple cashback rewards on everyday categories like utilities, dining, and groceries. It suits users who want to avoid high annual fees and benefit from easy renewal fee waivers. The card also offers flexible redemption options and is a good choice for moderate spenders looking for straightforward rewards without complex conditions.
Who should pick Shaurya Sbi Rupay Platinum Credit Card?
Consider Shaurya Sbi Rupay Platinum Credit Card if you spend significantly on dining, groceries, movies, and departmental stores and want to maximize rewards in these categories. The card is suitable for users who can meet the higher spending threshold to waive the annual fee and want the advantage of a welcome reward. If you value higher reward point multipliers and are comfortable with a slightly higher fee structure, this card offers better rewards potential.
Frequently Asked Questions
Hdfc Bank Upi Rupay Credit Card charges Rs.99 for both joining and renewal, with a waiver on renewal fee if you spend Rs.25,000. Shaurya Sbi Rupay Platinum Credit Card has an annual fee of Rs.250, waived if you spend Rs.50,000.
Shaurya Sbi Rupay Platinum Credit Card offers 5X reward points on dining and groceries with a higher cap, while Hdfc Bank Upi Rupay Credit Card offers 3% cashpoints with a lower cap on these categories.
Shaurya Sbi Rupay Platinum Credit Card provides 1000 reward points as a welcome gift upon payment of the first year's annual fee. Hdfc Bank Upi Rupay Credit Card does not offer any welcome benefits.
Both cards charge a forex markup fee of 3.5% on foreign currency transactions.
No, neither card provides domestic or international lounge access or milestone benefits related to travel.
Hdfc Bank Upi Rupay Credit Card allows redemption of cashpoints against statement balance, travel bookings, and shopping vouchers. Shaurya Sbi Rupay Platinum Credit Card allows redemption of reward points against card outstanding with a minimum redemption threshold.