Idfc First Millennia Credit Card vs Rbl Bank Platinum Plus Mastercard Credit Card: Which is Better in 2026?
 vs

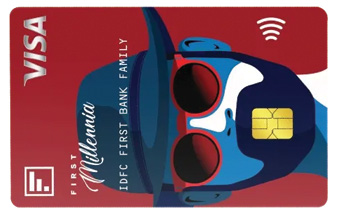
The Idfc First Millennia Credit Card and the Rbl Bank Platinum Plus Mastercard Credit Card cater to different user preferences. Idfc First Millennia offers zero joining and renewal fees with strong reward points and railway lounge access, while Rbl Bank Platinum Plus requires an annual fee waiverable on spending and focuses on basic reward points with limited lounge access. Both cards have distinct forex and fee structures that suit varied spending habits.
Comparison notes and quick badges use AI, grounded in the benefit data shown in the table. Confirm details on each issuer’s site.
Last updated:
| Feature | Idfc First Millennia Credit Card | Rbl Bank Platinum Plus Mastercard Credit Card |
|---|---|---|
| Bank | IDFC First Bank | RBL Bank |
| Network | Visa | MasterCard |
| Joining fee | No Joining Fees | — |
| Annual / renewal fee | No Annual Fee | Renewal Fee of Rs.999 |
| Annual fee waiver | — | Spend Rs.1 Lakh For Waiver of Annual Membership Fee |
| Reward rate (headline) | 3X Reward Points Upto Spends Rs.20000 | Earn 1 Reward Points per Rs.100 |
| Lounge — domestic | 4 Complimentary Railway Lounge Visits Per Quarter | 2 Complimentary Airport Lounge Access Per Year |
| Welcome benefit | Welcome Gift Voucher Rs.500 on Spending Rs.5000 | 4000 Reward Points on Payment of Annual Fee |
| Foreign currency markup | 0% - Zero Forex Markup | 3.5% - Foreign Currency Transactions |
Which is better for rewards?
The Idfc First Millennia Credit Card provides a more rewarding structure with 3X reward points up to Rs. 20,000 spend, and 10X points beyond that including on birthdays, making it attractive for users who spend regularly and want accelerated rewards. The Rbl Bank Platinum Plus Mastercard offers a flat 1 reward point per Rs. 100 spent, with 2X points on online spends capped at 1000 points, which is simpler but generally less rewarding. Additionally, Idfc First Millennia’s reward redemption rate is Rs. 0.25 per point, comparable to RBL’s, but the volume and bonus points favor the former for rewards enthusiasts.
Which is better for travel?
Idfc First Millennia stands out for travel benefits with 4 complimentary railway lounge visits per quarter, which is significantly higher than RBL Bank Platinum Plus’s 2 complimentary airport lounge accesses per year. Neither card offers international lounge access. The zero forex markup on Idfc First Millennia is a clear advantage for international travelers, whereas RBL Bank charges a 3.5% forex markup, making it less cost-effective for foreign currency transactions.
Which has lower effective cost?
Idfc First Millennia has no joining or renewal fees, making it more cost-effective for users who want to avoid annual charges. In contrast, RBL Bank Platinum Plus charges a Rs. 999 renewal fee that can be waived only if you spend Rs. 1 lakh annually, which may not suit low or moderate spenders. Both cards have late payment fees, with Idfc First charging 15% and RBL Bank 12.5%, but RBL Bank also imposes a Rs. 99 reward redemption fee and a 1.8% railway ticket purchase fee, which adds to the cost of usage.
Forex Charges Comparison
Idfc First Millennia Credit Card offers zero forex markup, making it more suitable for international travelers or those who frequently transact in foreign currencies. In contrast, Rbl Bank Platinum Plus Mastercard charges a 3.5% forex markup, increasing the cost of foreign currency transactions.
Fee Waiver Conditions
Rbl Bank Platinum Plus Mastercard requires an annual spend of Rs. 1 lakh to waive its Rs. 999 renewal fee, which may be restrictive for some users. Idfc First Millennia Credit Card has no joining or renewal fees, offering a simpler and more economical fee structure.
Who should pick Idfc First Millennia Credit Card?
Consider Idfc First Millennia Credit Card if you prefer a no-fee card with strong reward points especially on higher spends and birthdays, frequent railway travel with lounge access, and zero forex markup for international usage. This card suits users looking for a cost-effective, reward-rich option with travel perks focused on domestic railway lounges.
Who should pick Rbl Bank Platinum Plus Mastercard Credit Card?
Consider Rbl Bank Platinum Plus Mastercard Credit Card if you are comfortable paying an annual fee that can be waived with high spending, prefer simpler reward points on online spends, and want occasional airport lounge access. This card may appeal to users who primarily shop online and can meet the spend criteria to avoid fees, though forex costs and limited lounge access should be considered.
Frequently Asked Questions
No, the Idfc First Millennia Credit Card has no joining fees and no annual renewal fees.
Idfc First Millennia Credit Card has zero forex markup, while Rbl Bank Platinum Plus Mastercard charges a 3.5% forex markup on foreign currency transactions.
Idfc First Millennia offers 4 complimentary railway lounge visits per quarter, whereas Rbl Bank Platinum Plus provides 2 complimentary airport lounge accesses per year.
Yes, the Rs. 999 annual renewal fee is waived if you spend Rs. 1 lakh in the year.
Idfc First Millennia offers 3X reward points up to Rs. 20,000 spend and 10X points beyond that including on birthdays. Rbl Bank Platinum Plus offers 1 reward point per Rs. 100 spent, and 2X points on online spends capped at 1000 points.
Rbl Bank Platinum Plus charges a Rs. 99 fee for reward redemption, while no such fee is mentioned for Idfc First Millennia.